Microsoft Azure Revenue Jumps 48% as AI Capacity Expands
Microsoft Azure revenue jumped 48% in the company’s fiscal first quarter of 2027, reaching $33.17 billion as demand for cloud and artificial-intelligence computing continued to exceed available capacity.
Microsoft reported $92.3 billion in total revenue for the three months ended September 30, up 19% from a year earlier. The results pair rapid cloud growth with a capital-spending program that is becoming one of the defining costs of the AI infrastructure cycle.
The quarter produced four closely watched figures:
- Azure revenue rose to $33.17 billion.
- Total quarterly capital expenditures reached $45.2 billion.
- Microsoft Cloud revenue increased 30% to $63.9 billion.
- Commercial remaining performance obligations reached $677 billion.
Microsoft Azure Revenue Jumps to $33.17 Billion
Azure’s 48% increase was stronger than the preceding quarter and placed the cloud platform above the $32.84 billion consensus estimate compiled by Visible Alpha, according to Reuters. Microsoft’s official product table shows Azure revenue rising from $22.38 billion a year earlier.
The company now reports Azure as a standalone revenue line, giving investors a clearer view of the business that competes directly with Amazon Web Services and Google Cloud. Microsoft says the figure includes Azure cloud services and AI consumption, so it captures both conventional computing and workloads tied to generative AI.
Broader Microsoft Cloud revenue reached $63.9 billion, up 30%. Microsoft 365 commercial cloud revenue grew 17% on a reported basis, while the company’s new Agents and Infrastructure segment generated $76.8 billion, a 25% increase.
Microsoft’s scale also translated into higher earnings. Operating income rose 21% to $45.9 billion, while reported net income increased 32% to $36.6 billion. Excluding the effect of the company’s OpenAI investment, Microsoft calculated non-GAAP net income of $36.4 billion, up 18%.
AI Infrastructure Spending Reaches $45.2 Billion
Capital expenditures reached $45.2 billion during the quarter, including $39.4 billion of cash spending on property and equipment. Management said roughly three-quarters of the total covered short-lived assets such as CPUs, GPUs, memory and storage rather than land or buildings.
That mix shows how quickly Microsoft must replace and expand the computing layer behind Azure and Copilot. New facilities still matter, but advanced accelerators and the systems surrounding them absorb most of the near-term budget and can lose economic value faster than a data-center shell.
Microsoft opened 24 data centers across five continents during the quarter. Executives said AI demand continued to exceed capacity and that the company reduced the time required to bring GB300 systems online by 20% from the previous quarter while increasing Copilot throughput by 50%.
The infrastructure buildout is not slowing immediately. Management expects second-quarter capital expenditures to exceed $50 billion and estimated calendar-year spending of about $170 billion, partly because some third-party project costs shifted between periods.
Microsoft’s $677 Billion Backlog Tests Capacity Expansion
Commercial remaining performance obligations rose 73% to $677 billion. The measure covers contracted revenue that has not yet been recognized, giving Microsoft unusually strong visibility into demand while also increasing the importance of delivering capacity on schedule.
About 30% of the backlog is expected to be recognized within the next 12 months, and its weighted average duration is 2.3 years. The balance therefore represents a multi-year book of business rather than revenue Microsoft can record immediately.
The distinction matters because signed contracts do not remove construction, power and hardware constraints. Microsoft must install systems, connect facilities and make services available before much of that demand becomes reported sales. Delayed equipment or utility access can shift revenue even when customer commitments remain intact.
For the fiscal second quarter, Microsoft guided total revenue to between $96 billion and $97.1 billion. The company expects Azure growth of 49% to 50%, indicating that management sees another period of acceleration despite the scale of the comparison.
Cloud Growth Contrasts With Windows and Xbox Declines
The results were less uniform outside cloud infrastructure. Devices and Consumer revenue fell 3% to $15.5 billion, with Windows OEM and devices revenue down 22% and Xbox content and services revenue down 2%.
Search and news advertising revenue excluding traffic-acquisition costs grew 12%, offering a partial offset. The contrast leaves Microsoft increasingly dependent on cloud subscriptions, Azure consumption and AI services to carry company-wide growth while mature consumer businesses face tougher comparisons.
The next test is operational rather than promotional. Microsoft must turn an expanding contract backlog into available computing capacity without allowing depreciation, energy requirements and hardware replacement cycles to erode the economics of Azure’s growth.
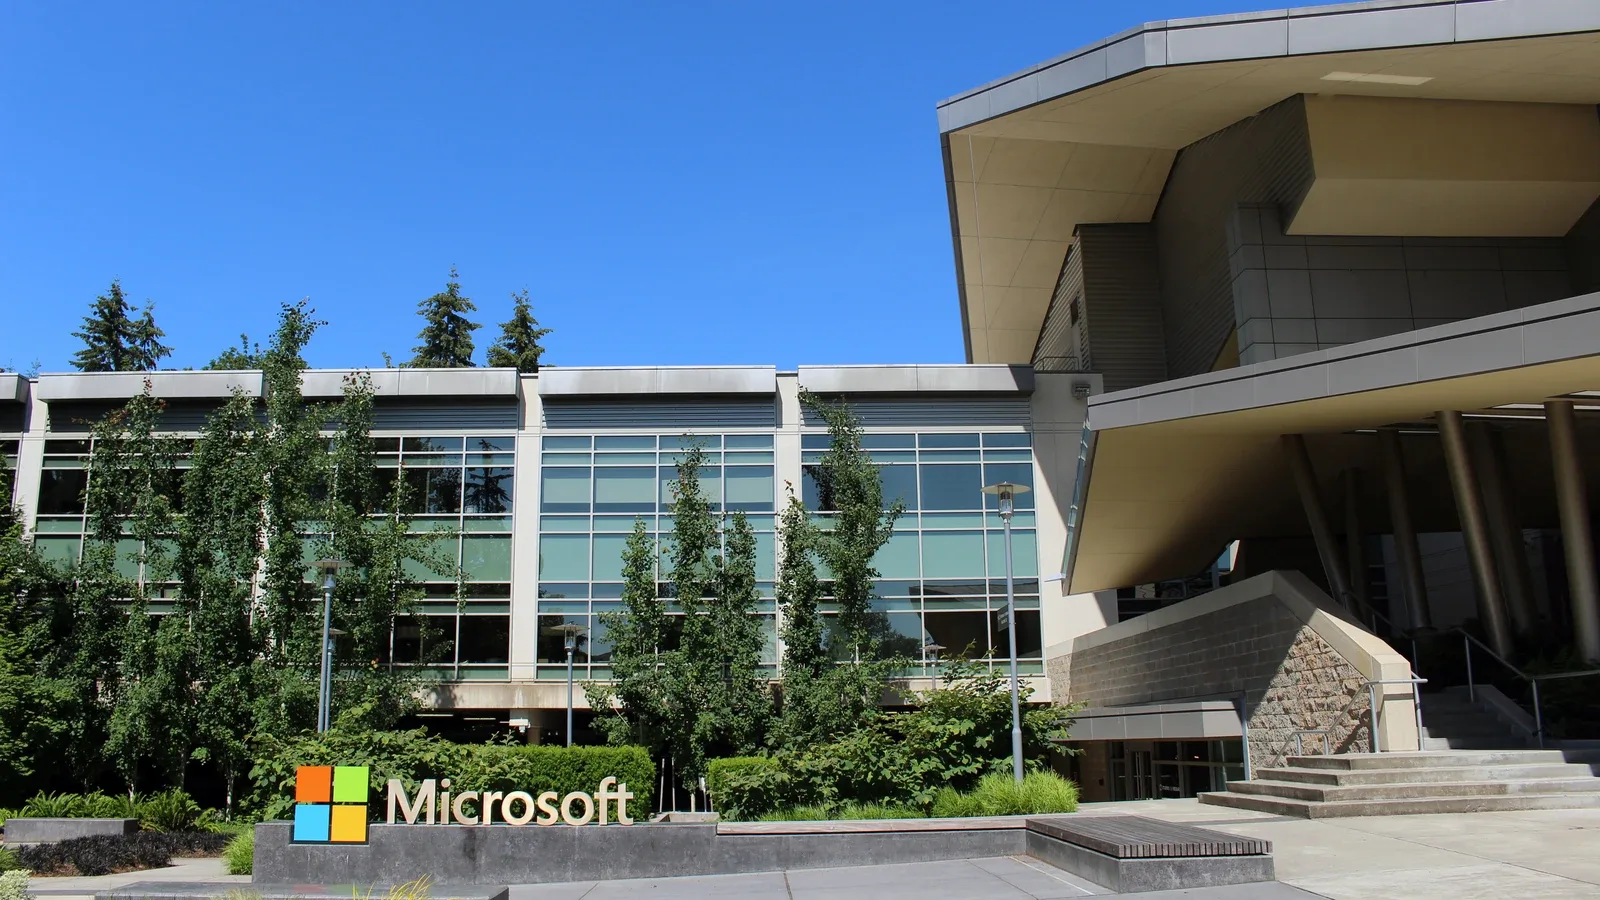
Feature image: Microsoft Building 92 in Redmond, photographed by Coolcaesar and sourced from Wikimedia Commons. Cropped, resized and converted to WebP; the derivative is distributed under CC BY-SA 4.0.